

Klarna: Smarter everyday money
by Klarna Bank AB (publ)
4.8
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.8
- Price
- Free
- Download
- 50.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
 Analysis by Getfullapps
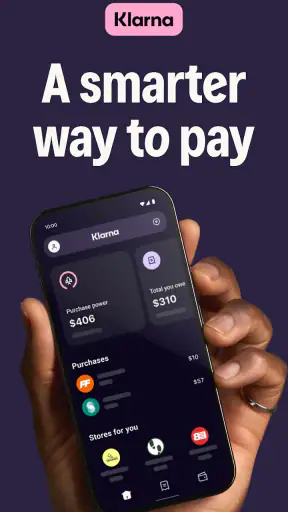
I approached Klarna: Smarter everyday money as a finance app rather than simply a shopping tool, and that distinction matters. Its main appeal is bringing spending, saving, cashback discovery, and the Klarna Card into one mobile experience. I found it most useful when I wanted a quick view of everyday money decisions without switching between several financial apps, although the experience is closely tied to an active internet connection and to how comfortable I am managing purchases inside a shopping-focused environment.
Developed by Klarna Bank AB (publ), the app is free and available to everyone from a content-rating perspective. It has grown into a very widely used service, with over 50 million installs and a 4.8 average from around 1.9 million ratings. Those figures suggest a mature product with a large audience, but they do not remove the need to decide whether its particular approach suits the way you handle money.
How Klarna feels when money decisions depend on a connection
The first thing I noticed is that Klarna works best as a connected financial dashboard. When the app can reach its services, browsing account information, exploring offers, checking available features, and moving between spending and saving areas feels naturally designed for a phone. The experience is less like opening a traditional bank website and more like using a live financial storefront that updates as I interact with it.
That connected design is convenient, but it also changes how I use the app. I would not treat it as the only place to keep essential payment information immediately before an important purchase. If I am standing at a checkout, travelling, or dealing with an unreliable signal, I prefer to have the relevant card or account details already available through the normal payment method I plan to use. Klarna is strongest when I prepare and review, rather than when I expect every financial action to work instantly in any network condition.
For example, imagine I am comparing prices during a lunch break. I can open the app, look through available shopping options, consider cashback opportunities, and decide whether using a Klarna-related payment option makes sense. That is a useful connected workflow. If the signal drops while pages are loading, however, the process can become uncertain at exactly the moment I want a clear answer. I would rather pause than assume that a purchase, offer, or account update has completed.
This is not a criticism unique to Klarna’s concept; modern finance services routinely rely on secure online communication. The important practical point is to recognize the difference between reviewing a financial choice and completing a time-sensitive payment. I use the app proactively, while I am still planning, instead of waiting until I am already at the final step of a purchase.
Shopping, saving, and the risk of blurred priorities
Klarna combines money management with shopping discovery, and that combination is both its most distinctive strength and its biggest behavioral trade-off. I like being able to explore ways to manage spending and savings in the same place, but a shopping-oriented interface can also encourage me to browse when I originally opened the app for a more serious financial task.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
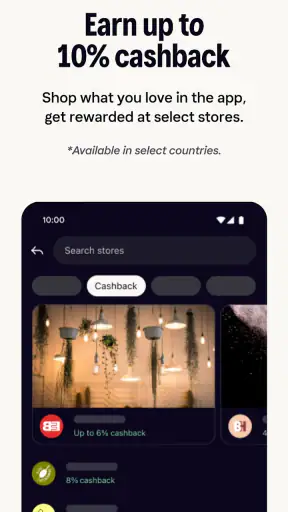
My practical solution is to give each visit a clear purpose. If I open the app to review spending, I deal with that first and avoid treating suggested shopping content as entertainment. If I am looking for cashback, I compare the actual value against the purchase I already intended to make. Cashback is only useful when it supports a planned purchase; it is not a reason for me to buy something I would otherwise skip.
This distinction is especially important for people who are trying to reduce impulse spending. Someone who wants a calm, banking-only environment may find Klarna’s blend of commerce and finance distracting. A conventional banking app or a dedicated budgeting tool can be a better fit when the priority is strict separation between account management and shopping discovery.
Using the app in everyday mobile situations
The mobile format makes the app convenient for short, focused checks. I can review a financial decision while commuting, compare an offer before ordering, or check a purchase plan before leaving a store. The screen is small, though, so I would not use a rushed glance as a substitute for reading the full terms of a payment choice or understanding how a transaction affects my budget.
One useful habit is to use a two-stage workflow. I first browse and gather the information I need, then I stop to decide whether the purchase belongs in my budget. This prevents the speed of a phone interface from turning a casual idea into an immediate commitment. It also makes the app’s connected nature work in my favor: I use the live information while I have a stable connection, rather than trying to improvise when the network is poor.
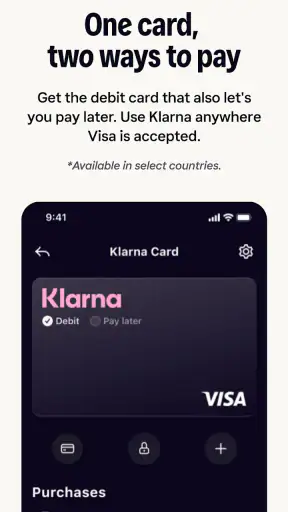
The Klarna Card is another reason someone might keep the app close at hand. The app presents it as part of the broader experience, so people interested in using that card can manage their relationship with Klarna from the same mobile home. I would still compare it with the cards and accounts I already use. Convenience is not automatically the same as better value, and the right choice depends on spending habits, repayment preferences, and the terms shown for the specific transaction.
I also appreciate that the app is not limited to one narrow money task. It can appeal to someone who wants a single place to explore savings and spending tools, but that breadth means I need to pay attention to the details of each feature instead of assuming that everything operates like a normal bank account. Before relying on any payment option, I would read the in-app information carefully and make sure I understand what I am selecting.
What I do when a page, update, or payment step fails
When a connected finance app behaves unexpectedly, the safest response is to verify rather than repeat the action immediately. If a purchase screen stalls, I check whether I received a confirmation, review the relevant account or transaction view when it becomes available, and avoid pressing the final action repeatedly. That simple discipline can prevent confusion about duplicate attempts or an unclear payment state.
If the app does not load, I first check the connection and try again later instead of assuming that the service or my account has changed. For an urgent purchase, I keep an alternative payment method available. Klarna is more useful to me when it is one part of my financial toolkit, not the only method I can use in a time-sensitive situation.
Recovery also means keeping records outside the moment of purchase. If I am arranging something important, I note the merchant, amount, and intended payment choice before completing the transaction. That gives me something concrete to compare with the app later if the connection fails during checkout. It is a small habit, but it makes a mobile finance workflow much less stressful.
I would also avoid making a financial decision based on a partially loaded screen. A missing detail can matter more than a fast interface. I wait for the relevant information to appear, especially when comparing payment choices, savings actions, or cashback conditions. The app encourages quick interaction, but responsible use requires slowing down at the points where money is committed.
Being careful with mobile data and attention
Because Klarna is designed around current account and shopping information, I use it when I have a reliable connection and enough time to read. On mobile data, I keep sessions focused: check the detail I need, make a decision, and close the app. This is not only about data usage; it also reduces the chance that I will drift from a budgeting task into unnecessary browsing.
For people with limited connectivity, the main adjustment is planning. I would review a purchase or offer before reaching a place where reception is uncertain, and I would not depend on the app as my sole source of information during travel. A screenshot or personal note can help me remember what I intended to check, but I would not treat an old image as proof that a live balance, offer, or transaction status remains unchanged.
Privacy-conscious users should apply the same care they would use with any finance app. I avoid opening financial information on a shared device, keep my phone protected, and do not rush through prompts simply to reach a shopping page. The app’s convenience is valuable, but money management deserves deliberate attention. A finance app should make decisions easier to understand, not encourage me to hand over attention without reading.
Another useful technique is separating discovery from approval. I can explore savings ideas or cashback possibilities during one session, then return later to decide. This reduces the pressure created by a live shopping environment and gives me time to compare the choice with my existing bank accounts or cards. In my experience, that pause is more valuable than any single convenience feature.
Who will get the most from Klarna?
I think Klarna suits people who already shop online or by phone and want spending-related tools in the same place. It is particularly appealing if I value quick access to cashback discovery, savings features, and the Klarna Card rather than maintaining completely separate apps for each part of that routine.
It can also work well for someone who is organized enough to set personal boundaries. I would recommend it to a friend who can distinguish a planned purchase from an attractive suggestion and who is willing to read the details before choosing a payment option. The app’s convenience becomes a strength when the user remains in control of the decision.
I would be more cautious about recommending it to someone trying to eliminate shopping triggers, someone who wants only a traditional current-account experience, or someone who needs dependable access in places with inconsistent connectivity. A dedicated bank app may be calmer for basic account management, while a budgeting app may offer a more focused way to categorize spending and set financial limits.
It is also not automatically the best replacement for every existing financial service. If I already have a card with benefits that match my routine, I compare the real terms rather than switching because the app looks convenient. Klarna’s value comes from the combination of its tools and the way they fit my habits, not from simply adding another payment brand to my phone.
What to expect from the current app
The app was released on November 1, 2018, and its current version is 26.29.240. It supports devices running Android 9 or later. That makes checking compatibility straightforward for Android users, although I would still keep the operating system and app updated before relying on a finance service for an important transaction.
The free price removes a barrier to trying the service, but “free” should not be confused with every financial action having identical conditions. I would inspect the details presented for each payment or card-related choice and compare them with familiar alternatives. The app can organize options clearly, yet the responsibility for choosing an appropriate option remains with me.
I found the large user base reassuring in one limited sense: this is not an obscure experiment that I would expect to disappear after a few weeks. Still, popularity does not tell me whether the service matches my financial priorities. The better question is whether I want shopping, savings, cashback, and card access connected in one place, and whether I am comfortable with the online nature of that setup.
My connectivity verdict
After using Klarna as a connected finance and shopping companion, I see its best role as a planning and management hub. It is convenient for checking options, organizing money-related activity, discovering cashback, and exploring the Klarna Card from a phone. The experience feels most dependable when I have a stable connection, time to read, and a backup payment method for urgent situations.
My main reservation is the same feature that makes it distinctive: finance and shopping sit close together. That can simplify a routine for a disciplined user, but it may be unhelpful for someone who wants strict spending separation. Network interruptions add another reason not to leave important payment decisions until the last second.
My recommendation is to use Klarna deliberately, not automatically. If you want a mobile-first way to connect savings, spending, cashback, and the Klarna Card, it is a compelling free app from Klarna Bank AB (publ). If your priority is a quiet banking tool, offline certainty, or strong protection from shopping temptation, a traditional bank app or dedicated budgeting service may serve you better. For me, the app earns its place when I use its connected features to make a considered decision rather than letting the convenience make the decision for me.
Pros
- User-friendly interface for easy navigation.
- Offers installment payment options.
- Provides price drop alerts.
- Strong customer support via chat.
- Secure transactions with encryption.
Cons
- Limited availability in some countries.
- Occasional app crashes reported.
- Some features require linking a bank.
- Notifications can be overwhelming.
- High late payment fees.
FAQs for Klarna: Smarter everyday money
What is Klarna and how does it work?
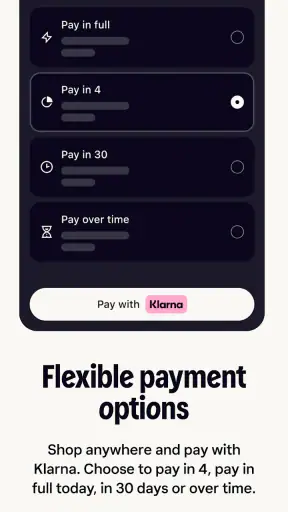
Klarna is a financial services app that allows users to shop, pay, and manage their money. It offers features like 'buy now, pay later,' where you can split purchases into interest-free installments. Users can connect their bank accounts, track spending, and access personalized deals, making it a versatile tool for managing everyday finances.
Is Klarna safe to use for online shopping?
Yes, Klarna is designed with security in mind. It uses advanced encryption and secure payment systems to protect your financial information. Additionally, Klarna’s buyer protection policy ensures that users are covered if something goes wrong with their purchase, adding an extra layer of security and peace of mind when shopping online.
What are the fees associated with using Klarna?
Klarna does not charge interest on its 'pay in 4' service if payments are made on time. However, missed payments may incur late fees. For other financing options, interest rates may apply, depending on the terms chosen. It's important to review the specific fees and terms associated with your selected payment plan.
Can I use Klarna for in-store purchases?
Yes, Klarna can be used for in-store purchases at participating retailers. Users can generate a one-time virtual card in the app to complete in-store transactions. This feature enhances the flexibility of Klarna, allowing for seamless integration into both online and offline shopping experiences.
How does Klarna affect my credit score?
Klarna performs a soft credit check for its 'pay in 4' service, which does not affect your credit score. However, for longer-term financing options, a hard credit check may be conducted, which could impact your credit rating. It's advisable to understand these implications before choosing a financing option through Klarna.
Read About Klarna: Smarter everyday money in Your Language

Klarna: Smarter everyday money
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via app@klarna.com, visit https://www.klarna.com, or review their https://www.klarna.com/international/privacy-policy/.










